For busy parents balancing daycare bills, rising grocery costs, housing payments, and uneven income, young families’ financial planning can feel like one more thing competing for attention. The real strain is that everyday family budgeting challenges keep pushing big decisions- protecting the household, reducing debt, and preparing for the future- into “later,” even when the stakes are already high. Clear financial goals for parents turn scattered money choices into a shared direction, and simple saving strategies for families create breathing room when surprises hit. A workable plan is how families build long-term financial security without needing perfect timing or extra money.
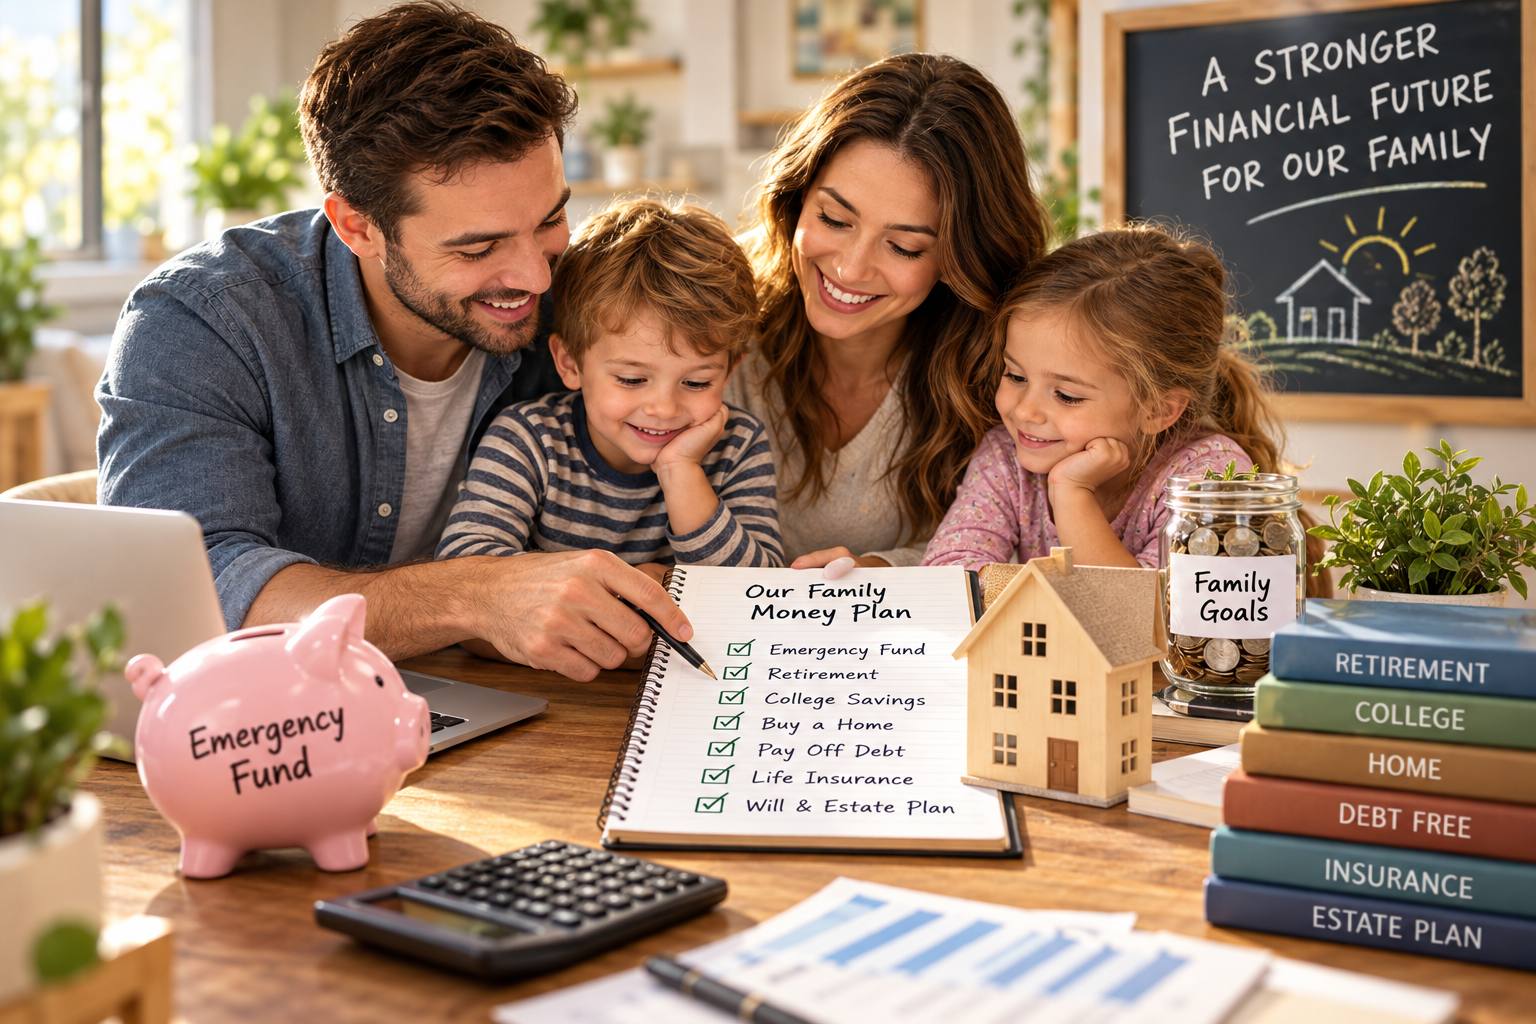
Build a Young Family Money Plan in 5 Steps
This simple sequence helps you cover today’s basics while protecting your family from the big “what ifs” that can derail progress. You will leave with a short, ordered checklist you can start today, even if money feels tight.
- Step 1: Start a small emergency fund first
Choose a starter target you can hit quickly, then automate a weekly transfer until you reach it. The CFPB notes that setting a goal can help you stay motivated, which is exactly what you need when you are building this habit from scratch. Keep the money in a separate savings account so it is available for surprises, not everyday spending. - Step 2: Turn retirement and college into automatic “background” savings
Start with retirement through a workplace plan or IRA, especially if there is any employer match, then add a small recurring college contribution if your budget allows. Pick one day each month to review contributions and increase them by even a tiny amount when raises or tax refunds arrive. The goal is consistency, not perfection. - Step 3: Map your home-buying path before you shop
Decide what monthly payment range fits your current life, then work backward to a down payment goal and a realistic timeline. Check your credit reports, estimate closing costs, and build a moving and repairs buffer so the first year of ownership is not a scramble. If buying is not near term, this step still helps you prioritize savings and avoid rushing into the wrong loan. - Step 4: Make a clear debt plan and protect your cash flow
List every debt with balance, interest rate, and minimum payment, then choose one payoff method and stick to it for 90 days before switching. Pay minimums on everything and send extra to one target debt so you can see progress. At the same time, stop adding new balances by setting a realistic spending cap for groceries, subscriptions, and kid expenses. - Step 5: Cover the “if something happens” basics: life insurance and a will
Choose term life insurance sized to replace income, cover childcare, and pay off major debts, then name beneficiaries that match your plan. The scale of the market shows how common this protection is, with life insurance protection widely used to shield families from income loss. Then draft a simple will and guardianship plan, so your wishes are clear, and paperwork is not left to guesswork.
Buffer Your Budget From Surprise Appliance and System Breakdowns
Once you’ve mapped out your core spending plan, the next win is protecting it from big, random repair bills. A home warranty can help steady your cash flow by covering repairs to major appliances and key home systems when they break down, so a failed fridge, HVAC issue, or other surprise doesn’t automatically turn into a budget emergency. Before you buy, read exactly what’s included and excluded, and review the plan’s appliance repair and replacement coverage so you know what kinds of breakdowns are handled. Also look for coverage that includes removal of defective equipment and repairs for breakdowns caused by improper installations or past repair work. With home costs better contained, you’ll be in a stronger position to weigh insurance choices, wills, and debt trade-offs next.
Money Safety-Net FAQs for Young Families
Q: How much should our emergency fund be right now?
A: Start with one month of essential expenses, then build toward three to six months as your steady target. If income is variable or you have higher medical or childcare costs, lean closer to six months. Automate a small weekly transfer and treat it like a non-negotiable bill.
Q: When does life insurance actually make sense for young parents?
A: It makes sense when someone relies on your income or unpaid caregiving, including a spouse, partner, or kids. A common first step is term life insurance sized to cover childcare, housing, and debts for several years. Get quotes, pick a term that matches your kids’ dependency window, and name beneficiaries.
Q: What basic estate planning documents should we have?
A: At minimum, most families need a will, guardianship nominations for minor children, and beneficiary updates on financial accounts. A simple estate planning process also looks at how assets transfer and who can make decisions if you are incapacitated. Schedule a short consult, then store copies where your trusted person can access them.
Q: How should we prioritize paying off debt while still saving?
A: Keep a starter emergency fund first so a surprise bill does not push you back onto credit cards. Then focus extra payments on the highest-interest debt while paying minimums on the rest. If you feel stuck, remember many people are not at all confident about big money goals, so choosing one clear method and sticking with it is a win.
Q: Should we pay off the mortgage early or invest more?
A: If you have high-interest consumer debt, tackle that before accelerating the mortgage. Once you have a solid cash buffer and no toxic-rate debt, you can split extra money between retirement investing and modest extra principal. A good tie-breaker is what helps you sleep: more liquidity, or a smaller required payment over time.
Family Finance Quick-Start Checklist
A checklist keeps your plan simple when life is busy, and it helps you spot the one move that matters most today. Since nearly half of Americans have no set financial budget, a few clear boxes to check can put you ahead fast.
✔ Set a weekly or bi-weekly auto-transfer to your emergency fund
✔ List your essential monthly expenses and your one-month target
✔ Choose one high-interest debt to attack with extra payments
✔ Increase retirement contributions by 1 percent if cash flow allows
✔ Price term life insurance quotes for each working parent
✔ Confirm beneficiaries on retirement accounts and insurance policies
✔ Draft a simple will and guardianship nominations
Pick one item now and schedule it in your calendar today.
Build Family Financial Security With One 30-Day Money Habit
Between bills, kid expenses, and long-term goals, money can feel like a constant tradeoff with no clear finish line. The way through is proactive planning, using simple routines that keep family budgeting, saving, protection, and paperwork moving forward without trying to fix everything at once. With steady follow-through, financial security stops being a vague hope and starts looking like visible progress and fewer surprises. Pick one next step and stick with it for 30 days.